Financial Health Check
Offerings
Learn
Resources
Compare plans from India's most trusted insurers, all in one place. Estimate your required cover in seconds.
Beyond the basics, our partner plans come with benefits built to protect your income, your health and your savings.
Simple, and high claim settlement ratio, so your family gets paid quickly when it matters most.
Plans with accidental death cover benefit on top of your base cover, boosting the payout if death results from an accident.
Selection of plans that cover up to 34 critical illnesses at a fixed premium, plus a 100% payout on diagnosis of a terminal illness.
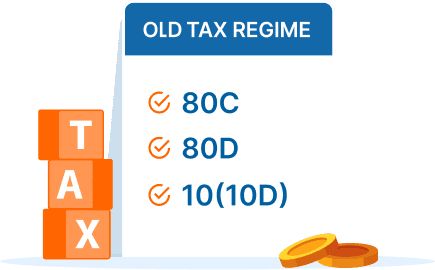
Premiums and benefits may qualify for deductions and exemptions under Sections 80C, 80D and 10(10D) in the old tax regime, subject to prevailing tax law.

Use the life insurance calculator to find your ideal protection amount.

Compare life insurance plans and choose what suits your needs the best.

Buy life insurance directly from the insurer online, without any paperwork.
Enter the values in the fields and we will estimate the total cover you will need to keep your family financially secure.
Your result is locked
Fill in your details and verify your mobile number with the OTP to view your estimate.

This is an indicative estimate only. Actual premiums vary by insurer, plan features, age, health, and lifestyle habits. All figures are exclusive of GST.
Life insurance pays a lumpsum (sum assured) to your nominees upon death, in exchange for premiums. You need it if anyone depends on your income to replace earning capacity for a family's lifestyle, debts, children's education, and daily expenses.
Under the Human Life Value approach, life cover usually should be 10 to 15 times your annual income. However, for better accuracy, you may calculate required cover using the Life Insurance Calculator, plus loans and future goals like children's education. For example, with ₹12 lakh income, ₹30 lakh loan and ₹20 lakh education goal, ideal cover may be ₹1.7 to 2.3 crore.
Term plan gives pure protection, lowest premium, and no maturity benefit. Endowment: insurance + guaranteed savings, maturity benefit, much higher premium. ULIP offers insurance + market-linked investment, part premium invested in equity/debt funds. Experts recommend term insurance is a must if your family is dependent on your income.
Term plan covers a fixed period at the most affordable premium. A healthy 30-year-old can get ₹1 crore for approx. ₹700 to 1,000/month (depending on certain conditions). Most recommended due to highest coverage-to-premium ratio - maximum protection at minimal cost. No maturity payout.
Three stages: Premium Payment - Section 80C deduction up to ₹1.5 lakh. Death benefit - fully tax-free under Section 10(10D). Maturity benefit - tax-free under 10(10D) if annual premium ≤ ₹5 lakh (policies post April 2023) under old tax regime only.
Term insurance: lapses after a 30-day grace period; no refund. Traditional plans: if 2-3 years paid, acquire paid-up value with reduced coverage. ULIPs: fund value stays invested, charges deducted; surrender after 5 years.
Yes, online purchase is IRDAI-regulated and 5-10% cheaper (no agent commissions). Claim process identical: nominee submits death certificate, claim form, policy, KYC. Insurers must settle within 30 days per IRDAI norm. Online term plans show 97-99% CSR.
Riders are add-on benefits at extra premium: Accidental Death Benefit, Critical Illness (cancer, heart attack, stroke), Waiver of Premium (on disability), Terminal Illness (advance payout). More cost-effective than separate policies.
The most financially dependent person typically spouses, children, or parents. Minors need an appointee. Update nominee after major life events. Without a nominee, payout enters legal estate and follows succession laws, causing delays.
Nominee is designated in the policy to receive the payout and acts as a custodian. Legal heir is entitled to assets under succession law. Supreme Court has clarified nominees are trustees; legal heirs can contest. Align nominee with your Will.
Grace period: 30 days (annual/semi-annual) or 15 days (monthly) after due date the coverage continues. Revival period: up to 5 years from first unpaid premium - restart lapsed policy by paying arrears + interest, possibly fresh medical exam.
Yes. Homemakers provide significant economic value through childcare, household management, and eldercare estimated at ₹3-8 lakh per year (or higher in urban India). A ₹25-50 lakh term plan for a 30-year-old can cost roughly ₹3,000-6,000 annually. This ensures that the surviving spouse can manage the cost of replacing these essential services.
Step 1: Nominee intimates claim. Step 2: Submit death certificate, policy, claim form, KYC, FIR (if accidental). Step 3: Insurer verifies (claims more than 3 years old cannot be challenged except fraud). Step 4: IRDAI mandates payout within 30 days after all the documents are received. Investigation must be completed in 90 days.
Not essential right now. But consider a small term plan if you have loans with co-signers, plan future dependents (locks in lower premiums), or employer life insurance is your only coverage (ends when you leave). Early purchase avoids health-related denials.
Term insurance covers you for a fixed period and pays only if death occurs during the policy term, so premiums are low. Whole life covers you up to 99 to 100 years, includes a savings value and costs much more. Term suits income protection while whole life suits estate planning.
Insurance is the subject matter of solicitation. airpay money acts solely as a distributor and does not underwrite or assume any risk under the policies. We do not provide any recommendation, advice, or endorsement of specific insurance products; customers are advised to evaluate their needs independently before making a purchase decision.